How Much House Can I Afford in Aiken? (A Budget-Friendly Reality Check)
Wondering how much house you can afford in Aiken, SC? Here's a simple, no-stress way to figure out your real budget before you start touring homes.
Every home search starts with the same question, usually typed into Google at 11 p.m. with a bowl of cereal: how much house can I afford?
The internet will hand you a dozen calculators that spit out a big, shiny number. Some of them are a little too generous. So let's talk about what you can afford on paper, what you can afford in real life, and why those two numbers are sometimes very different.
Start with what the lender sees
Lenders mostly care about your debt-to-income ratio, or DTI. That's your total monthly debt payments (car, student loans, credit cards, and your future house payment) divided by your gross monthly income.
Many loan programs like to see your total DTI somewhere around 43% or lower, though some will stretch higher with good credit or savings in the bank. So if your household brings home $7,000 a month before taxes, a lender might be comfortable with about $3,000 a month in total debt payments. If you already pay $600 for a car and $200 on student loans, that leaves roughly $2,200 for your mortgage payment.
That $2,200 has to cover more than the loan, though. Your monthly payment usually bundles four things together, which lenders call PITI:
- Principal: the part that pays down your loan
- Interest: the part that pays the bank
- Taxes: property taxes, held in escrow
- Insurance: homeowners insurance, and mortgage insurance if you put less than 20% down
Here's some good news if you're buying in Aiken. South Carolina taxes owner-occupied homes at a 4% assessment ratio, which keeps property taxes on a primary home pretty friendly compared to a lot of the country. (Just make sure you actually apply for it. More on that in our property tax post.)
Now look at what your life sees
The lender's number is the ceiling. Your comfortable number might be lower, and that's perfectly fine.
Ask yourself a few honest questions:
- Do I want to keep putting money into retirement every month?
- How often do I travel, eat out, or buy horse feed? (This is Aiken. Someone reading this has a horse.)
- Is a baby, a new car, or a career change coming in the next few years?
- How much cushion do I want in savings after closing?
A good gut check: pull up your bank statements from the last three months and see what you actually spend. If the new house payment plus your normal life leaves you with breathing room, you're in a great spot.
Don't forget the cash you need up front
Affordability includes the money you bring to the closing table. Plan for:
- Down payment: anywhere from 0% (VA and USDA loans) to 3% to 3.5% (many conventional and FHA loans) and up
- Closing costs: often around 2% to 5% of the price in South Carolina, which includes the closing attorney (yes, SC requires one)
- Inspections and appraisal: about $600–$900 each
- Moving and setup money: curtains, a lawnmower, and the inevitable Lowe's runs
What that looks like in Aiken
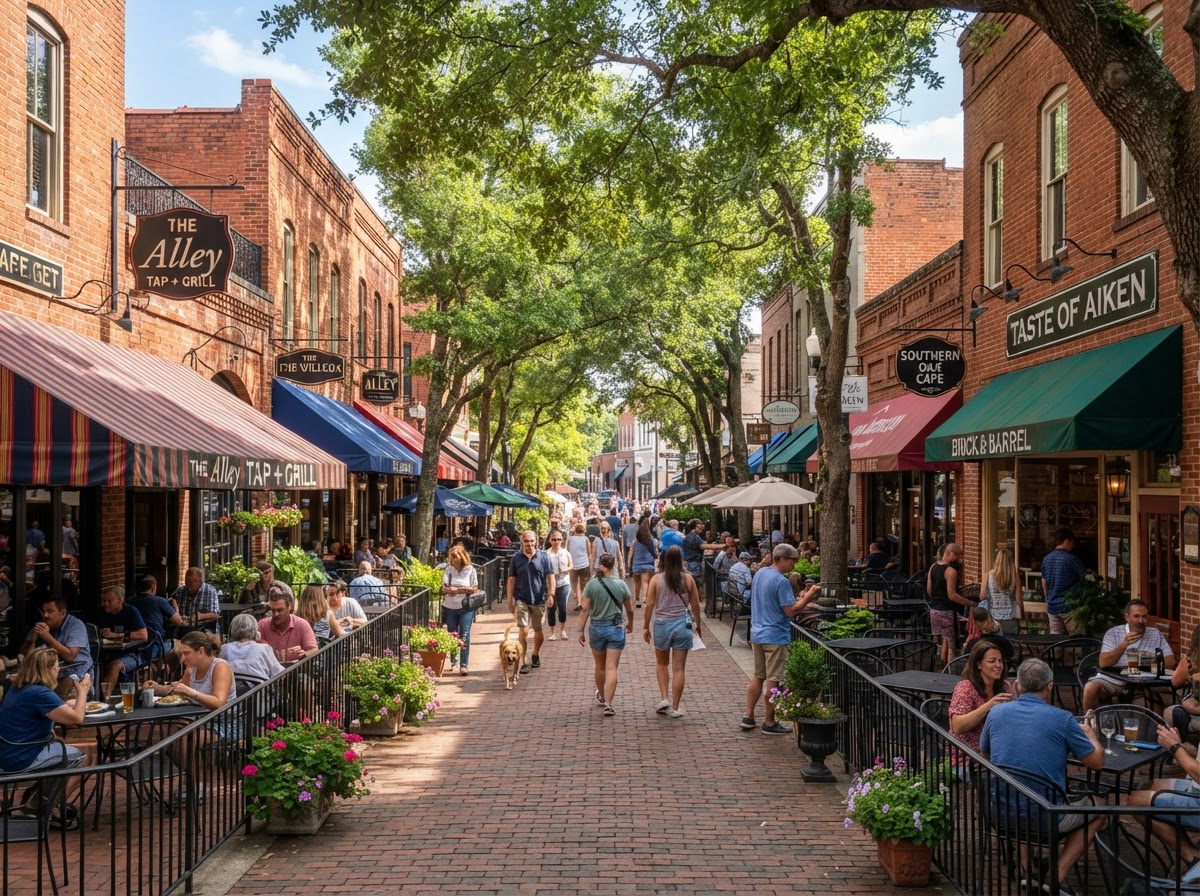
The median sold price for a home in the City of Aiken was $323,000 in October 2026, according to our local MLS. That gives you a useful benchmark. With a modest down payment and today's rates, a home around that price lands in a range a lot of Aiken families can work with, and there are plenty of homes well above and below it.
Aiken also gives you options at different price points. You might find an older brick ranch in town, a newer build on the north side, or a little more land out toward Windsor or Wagener for the same money. Your budget stretches differently depending on where you look, which is a big part of why I love working here.
The easiest next step
Get pre-approved with a local lender. It's free, it doesn't commit you to anything, and it turns a guess into a real number. Then sit down with your agent (hello, that's me!) and match that number to neighborhoods that fit your life.
If you'd like a list of lenders I trust or want to see what your budget buys in Aiken right now, reach out. I'm happy to help you find your number before you fall in love with a house that's out of it.